
The new steel measure
The EU's steel safeguard, introduced in 2019 to counter import surges driven by the US Section 232 tariffs and global overcapacity, expires at the end of June and cannot be extended under WTO rules. Yet global steel overcapacity is projected to grow from around 602 million tonnes in 2025 (already roughly five times EU demand) to 721 million tonnes by 2027. A new permanent tariff-rate quota regime (new steel measure) will take its place, cutting duty-free imports by nearly half, doubling the out-of-quota duty to 50%.
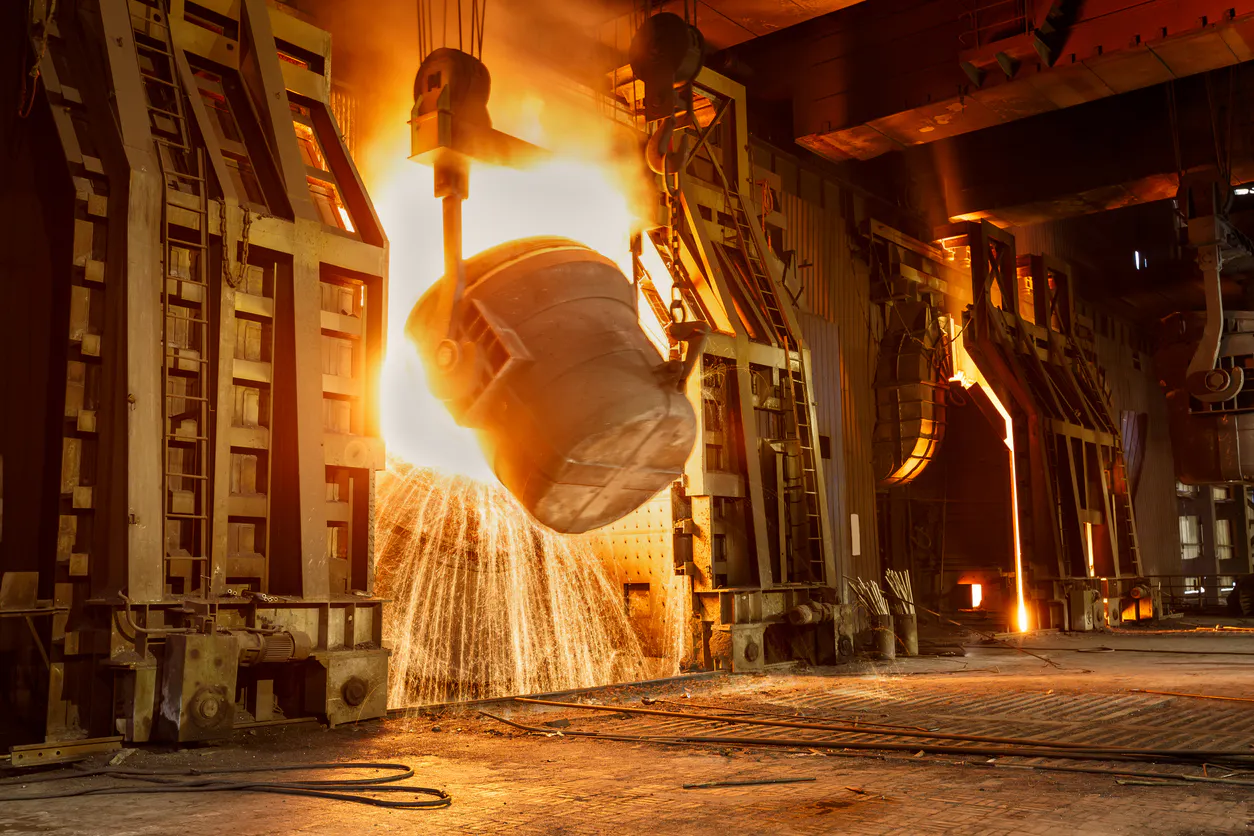
Sitting alongside these changes to the quota regime is the new "melt and pour" requirement. Steel production begins with iron and/or scrap being melted in a furnace and cast into its first solid form before being further processed into finished products. Under the new regime, importers will have to declare the country where the initial melt and pour took place, which may differ substantially from the country where the steel was last processed or exported from. The requirement seeks to tackle a well-known circumvention problem whereby steel melted and poured in overcapacity countries, such as China, is processed elsewhere and exported to the EU under the latter's quota after only minimal transformation.
The requirement will be phased in, starting as an information obligation, but it is expected to become more consequential over time. From 1 October 2026, importers must provide evidence of the country of “melt and pour”, such as via mill test certificates, already widely used in the sector (albeit voluntarily) to share product quality and technical information. From 1 October 2027, the Commission must "take into account" this information when allocating country quotas, and, within two years of entry into force, assess whether “melt and pour” should be the formal basis for determining quota allocation.
Supply chain re-adjustments
Today, steel takes the origin of the country where it was last "substantially transformed such as the local value added or whether processing was sufficientunderwent its last substantial processing or working, typically through a sufficient share of local value added, or processing significant enough to move the product into a new tariff category. Using the country of “melt and pour” to allocate quotas would reverse this logic by making the steel product fall under the quota of the country where it was first cast from liquid into solid form, regardless of subsequent processing. How this would work in practice, whether it would apply across the board or only where there is evidence of circumvention, is not yet clear.
The EU would not be the first to move in this direction: the US introduced “melt and pour” reporting in 2020, and imposed 25% duties on steel arriving from Mexico that had been melted and poured outside North America, Canada has applied a 25% surtax to steel “melted and poured in China” since July 2025, and the UK is currently exploring similar requirements.
The supply chain implications could be meaningful. Producers will need to know, and prove, where their steel was originally melted, which could impact sourcing strategies built around third-country processing. EU importers may end up favouring suppliers able to provide reliable melt and pour evidence, with smaller producers likely to feel this most acutely. How demanding compliance proves to be will depend on the type of evidence required, to be specified by the Commission by 31 August 2026, and on whether the measure is extended to downstream steel products following the June 2027 scope review.
A double-edged sword for decarbonisation
These supply chain re-adjustments matter beyond trade. According to Steel excess capacity is a joint study by Carbon4 and the European Climate Foundation, nearly half of the EU's consumption-based emissions are imported, around 20% of which comes from China, with much of it tied to metals and mining. By targeting drag on steel from overcapacity countries, where decarbonisation. Steel production is on average more carbon-intensive in overcapacity countries than in members of the Global Forum on Steel Excess Capacity (GFSEC), including thean OECD-hosted international platform for collective action on global steel excess capacity. Moreover, by depressing prices and squeezing margins, excess capacity further constrains EU safeguard producers' ability to invest in cleaner production, in a sector where several low-carbon steel projects have already been put on hold. The new steel measure could help reduce that footprint. ease some of this pressure and give the EU industry breathing space to decarbonise, if accompanied by the necessary investments.
But the calculation cuts both ways: third-country producers facing higher compliance costs and reduced duty-free access to the EU may lose the important revenues and demand signals they rely on to invest in cleaner production, with implications for global steel decarbonisation. This is particularly important as exporters must also continue to navigate a growing web of regulatory measures that make accessing the EU market increasingly challenging. These include emissions reporting obligations and a carbon levy under the Carbon Border Adjustment Mechanism (CBAM); ecodesign requirements under the Ecodesign for Sustainable Products Regulation (ESPR), including a Digital Product Passport (DPP) and a low-carbon steel label; and metal scrap export restrictions under the revised Waste Shipment Regulation. As a Europe Jacques Delors paper highlights, without a coordinated approach, the cumulative weight of these requirements risks falling disproportionately on smaller producers that often lack the necessary technical and financial capacity to comply.
Under CBAM, producers must monitor, report, and verify (MRV) embedded emissions or face punitive default values that will rise progressively, translating into higher CBAM charges over time. Without verified data, even cleaner producers will be charged on the basis of defaults rather than their actual performance. Emissions accounting will only become more challenging as the scope expands to downstream products and pre-consumer scrap inputs from 2028.
Under the ESPR, certain steel products will need to meet performance and information requirements likely to cover substances of concern, carbon footprint, recycled content, and origin (including melt and pour), carried throughout the product's life via a DPP. A low-carbon steel label is also being developed, classifying steel products by carbon footprint into performance classes. Only products meeting the low-carbon threshold under this label will qualify for incentives and preferential public procurement under the Industrial Accelerator Act, and the label may, over time, become a de facto standard for accessing other parts of the EU market.
Compliance is technically demanding. A TULIP Consulting study on the Indian steel sector illustrates that, while larger producers can generally engage in emissions accounting, smaller ones often cannot, and chain-of-custody traceability is a challenge even for big players. Most of the data needed is generated upstream in the value chain rather than by the EU importer, and many producers still rely on paper-based processes or fragmented IT systems, and the structured, verifiable data DPPs and CBAM demand is not yet standard practice. The picture is further complicated by tightening EU scrap export restrictions, on which Indian producers rely to decarbonise their own production.
A balancing act
Overcapacity is weighing on a struggling EU steel sector, with both trade and climate implications. By tackling overcapacity through reduced quotas and new “melt and pour” measures to prevent it, the new steel measure seeks to alleviate some of that pressure. However, this new regime sits alongside a growing web of regulatory measures, which together may strain trading partners, particularly smaller players, who are already struggling to navigate the current context and meet their own decarbonisation objectives.
Many of the objectives behind the EU's steel strategy – fighting global excess capacity, decarbonising heavy industry, and advancing circularity – cannot be achieved by the EU acting alone. As more jurisdictions adopt similar requirements, from “melt and pour” to carbon pricing and DPPs, cooperation on methodology alignment and interoperability of traceability systems becomes ever more pressing, both to ensure the effectiveness of these measures and to consolidate the EU’s external relationships in a fragmenting global economy, making cooperation with trading partners essential. Like excessive trade deficits or surpluses, steel overcapacity is a global problem in search of a global solution, and unilateral trade measures can only be a second-best fix with both positive and negative externalities, making continued cooperation through platforms like the GFSEC critical.
As carbon pricing and border carbon adjustments, low-carbon and circularity requirements, and DPPs are being adopted or considered in other jurisdictions, the Commission should actively pursue technical alignment with partners: carbon accounting methodologies and MRV to facilitate CBAM compliance, interoperability of IT systems through which DPPs and similar instruments will operate, and traceability obligations such as melt and pour reporting. Without such cooperation, the cumulative impact of these measures risks undermining both their own effectiveness, creating a spaghetti bowl of requirements hard to navigate by EU importers and steel producers in partner countries alike, and risks further straining the EU's trade relations in a fragmenting global economy.
Doing so will not be easy in the current geopolitical context. The challenge will be to strike a balance between competing objectives: protecting a struggling EU steel sector and tackling overcapacity, while accommodating downstream industries that depend on competitive steel inputs; accelerating decarbonisation at home without undermining decarbonisation efforts in partner countries; and safeguarding EU steel competitiveness without alienating trading partners or weakening the EU’s wider trade and climate agenda.